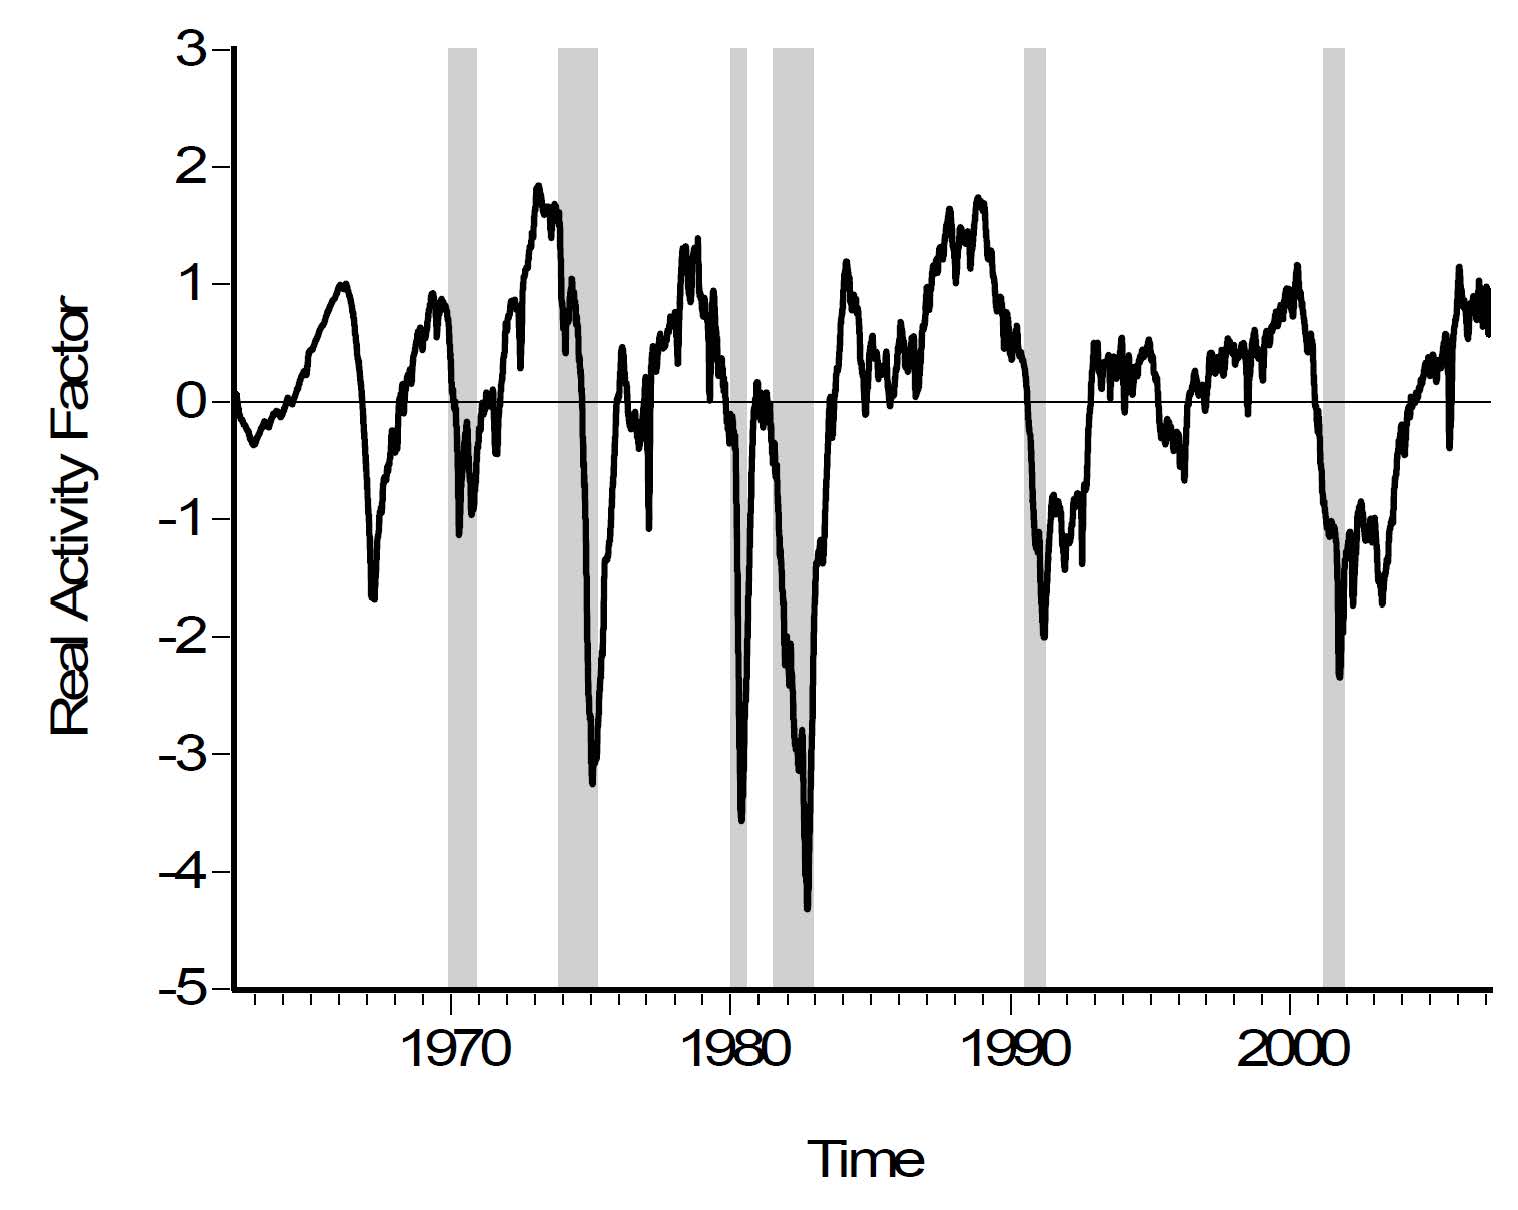
We construct a framework for measuring economic activity at high frequency, potentially in real time. We use a variety of stock and flow data observed at mixed frequencies (including very high frequencies), and we use a dynamic factor model that permits exact filtering. We illustrate the framework in a prototype empirical example and a simulation study calibrated to the example.
First Draft : March 2007
As of January 9, 2009, the Federal Reserve Bank of Philadelphia started producing the Aruoba-Diebold-Scotti Business Conditions Index based on the methods developed in this paper.
Paper
NBER Working Paper 14349 [September 2008]
Most Recent Working Paper (may not be identical to the published version)
Published Version (requires subscription)
Additional Materials
Press Mentions
Dow Jones Newswires [January 9, 2009]
The Press of Atlantic City [January 11, 2009]
Philadelphia Inquirer [January 15, 2009]
Econ Browser (James Hamilton’s Blog) [April 15, 2009]
Capital Spectator [November 20, 2009]
Philadelphia Inquirer [January 29, 2010]