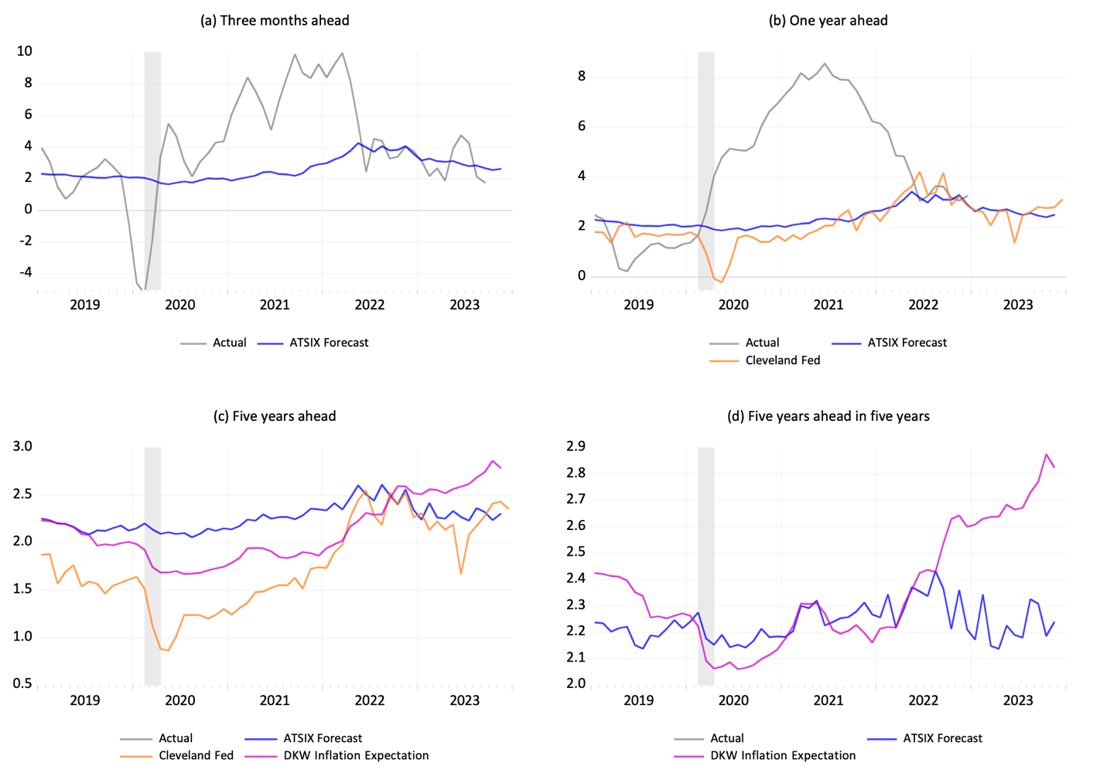
This chapter examines various measures of inflation expectations from surveys of professional forecasters and financial markets in the United States from 1998 to 2023. These measures span different horizons, forming a term structure of inflation expectations analogous to a yield curve. The analysis includes survey-based measures, a continuous term structure developed by Aruoba (2020), and market-based measures like swap rates and TIPS break-even rates. The chapter conducts a forecast comparison, finding that professional forecaster measures outperform market-based and model-based measures. Additionally, it analyzes inflation expectations during the Great Recession and the COVID-19 pandemic, revealing that while short-term expectations are often inaccurate during sudden events, long-term expectations remain stable.
Paper